
IBDP Economics 3.2 Variations in economic activity—aggregate demand and aggregate supply HL Paper 1 - New Syllabus
Question
(a) Using the Keynesian multiplier, explain how an increase in government spending can result in short-term economic growth. [10]
(b) Using real-world examples, evaluate the view that high economic growth rates can only be achieved at the expense of other macroeconomic objectives. [15]
Most-appropriate topic code (CED):
• TOPIC 3.3: Macroeconomic objectives – part (b)
▶️ Answer/Explanation
(a) Answer:
Short-term economic growth is an increase in real GDP resulting from an increase in actual output in the economy. One way in which the government can generate short-term growth is by increasing government spending, which is a component of aggregate demand.
The Keynesian multiplier explains how an initial change in an injection into the circular flow of income can lead to a larger final change in real GDP. Government spending is an injection into the circular flow of income.
Aggregate demand can be expressed as:
AD = C + I + G + (X − M)
Therefore, an increase in government spending directly increases AD. For example, if the government spends more on infrastructure, firms receiving government contracts gain additional revenue. These firms may increase production and employ additional workers.
The workers receiving additional income then increase their consumption. This additional consumption becomes revenue for other firms, allowing those firms to increase production and incomes. Some of the additional income is then spent again, creating further increases in consumption and output.
This process continues through several rounds of spending. Each round is smaller than the previous one because households do not spend all of their additional income. Some income is withdrawn from the circular flow through saving, taxation and spending on imports.
The size of the multiplier therefore depends on the proportion of additional income that is spent on domestic goods and services. A higher marginal propensity to consume (MPC) results in a larger multiplier, while a higher marginal propensity to withdraw (MPW) results in a smaller multiplier.
In its simplest form, the expenditure multiplier can be represented as:
Multiplier = 1 / (1 − MPC)
Alternatively, where withdrawals are considered:
Multiplier = 1 / MPW
For example, suppose the government increases spending by $10 billion and the multiplier is 2. The eventual increase in real GDP could be approximately:
$10 billion × 2 = $20 billion
The initial increase in government spending therefore produces a larger eventual increase in real GDP because the spending generates additional rounds of income and consumption.
An AD/AS diagram can show the initial increase in government spending shifting AD to the right. The multiplier process leads to a further increase in AD, resulting in a larger increase in real GDP.
The extent to which this produces short-term growth depends on the economy’s spare capacity. If the economy is operating below full employment, firms can respond to increased demand by increasing output and employment. Consequently, real GDP increases.
If the economy is already close to full employment, however, the multiplier effect may generate greater inflationary pressure rather than an equivalent increase in real output.
Therefore, an increase in government spending can generate short-term economic growth because it initially increases aggregate demand and then produces a larger final increase in real GDP through successive rounds of spending generated by the Keynesian multiplier.
(b) Answer:
Economic growth is an increase in real GDP over time. Other macroeconomic objectives commonly include low and stable inflation, low unemployment, a more equitable distribution of income, environmental sustainability and a sustainable external position.
The view that high economic growth can only be achieved at the expense of other macroeconomic objectives suggests that there are unavoidable trade-offs between rapid growth and goals such as low inflation, environmental sustainability, income equality, employment and a balanced trade position.
One potential conflict is between high economic growth and low inflation. If high growth is caused by a rapid increase in aggregate demand, firms may experience rising demand for goods and services. When the economy is close to full capacity, firms may respond by increasing prices, creating demand-pull inflation.
In an AD/AS framework, a rightward shift of AD can increase both real GDP and the price level, particularly when the economy is operating close to its productive capacity.
For example, during periods of rapid post-pandemic recovery, strong increases in aggregate demand in many economies contributed to inflationary pressures, particularly when supply constraints were also present. This demonstrates how rapid demand-led growth can create a conflict with the objective of price stability.
However, high economic growth does not necessarily cause inflation. If growth is driven by an increase in productive capacity, LRAS shifts to the right. The economy can then produce more output without the same degree of inflationary pressure.
Investment in technology, infrastructure, education and skills can increase productivity and allow potential output to grow. Thus, long-term supply-side growth may be compatible with low and stable inflation.
A second possible conflict is between high economic growth and environmental sustainability. Higher production may require greater use of energy and natural resources. If the additional production depends on fossil fuels, rapid economic growth can lead to higher carbon emissions, pollution and resource depletion.
China provides an example of this potential conflict. Rapid industrialization and economic growth produced large increases in income and living standards, but also contributed to significant environmental pressures, including high carbon emissions and air pollution.
Nevertheless, economic growth does not necessarily have to damage the environment. Governments can encourage green growth through renewable energy investment, energy efficiency, carbon pricing and technological innovation.
If technological progress allows firms to produce more output with fewer resources and lower emissions, economic growth can occur alongside environmental improvements. Therefore, the relationship between growth and sustainability depends partly on the composition and technology of production.
A third possible conflict concerns income distribution. High economic growth increases average income, but the gains may not be distributed equally. Growth concentrated in capital-intensive industries or high-skilled sectors may disproportionately benefit wealthy households and highly skilled workers.
As a result, rapid growth may be accompanied by increasing income inequality. This would create a potential conflict with the macroeconomic objective of greater equity.
However, governments can use progressive taxation, transfer payments and targeted public expenditure to redistribute some of the gains from economic growth. Investment in education and healthcare can also broaden access to the benefits of growth.
Therefore, economic growth and greater equity are not necessarily incompatible. The distributional impact depends on the structure of growth and the policies used by the government.
High economic growth can also have a positive effect on employment. When growth is driven by increased aggregate demand, firms increase production and demand more labour. This can reduce cyclical unemployment.
For example, during an economic recovery, increased consumption and investment can encourage firms to expand production and hire additional workers. Growth can therefore directly support the objective of low unemployment rather than conflict with it.
However, growth based on technological change and automation may increase structural unemployment if workers lack the skills required for newly created jobs. Therefore, the employment effect depends on the source of economic growth and the flexibility of the labour market.
Another potential conflict is between high economic growth and a balanced trade position. If growth is driven mainly by higher domestic consumption and investment, demand for imports may increase. If exports do not rise sufficiently, the trade balance may deteriorate.
However, growth can instead improve the trade balance if it is export-led. Investment in productivity and competitiveness can enable domestic firms to increase exports, generating foreign exchange earnings and potentially improving the current account.
High economic growth can also improve the government’s fiscal position. Higher employment and incomes can increase tax revenues, while lower unemployment may reduce government spending on unemployment-related benefits. Consequently, economic growth can help reduce government debt relative to GDP.
The extent of the potential conflicts therefore depends heavily on the source of economic growth. Demand-led growth when the economy is close to full employment is more likely to create inflation. Supply-side growth based on productivity improvements can increase potential output while reducing inflationary pressure.
Similarly, growth based on fossil-fuel-intensive production is more likely to conflict with environmental sustainability than growth based on renewable energy and cleaner technologies.
The time period also matters. In the short run, an increase in AD may increase real GDP and employment but create inflationary pressure. In the long run, investment and technological progress can increase LRAS and allow the economy to achieve sustained growth without the same inflationary effects.
Overall evaluation: The statement that high economic growth can only be achieved at the expense of other macroeconomic objectives is too absolute. Rapid demand-side growth can create inflationary pressure, environmental damage, greater inequality and potentially a deterioration in the trade balance.
However, high economic growth can also help achieve other objectives. It can reduce unemployment, increase government tax revenues and improve living standards. If growth is driven by increases in productive capacity, it may occur with relatively little inflationary pressure. If it is export-led, it may improve the trade balance, while green technologies can allow growth to occur alongside environmental sustainability.
The relationship therefore depends on the cause, speed and quality of growth, the economy’s available spare capacity and the policies implemented by the government.
Thus, high economic growth does not inevitably require sacrificing other macroeconomic objectives. The greatest conflicts are likely when growth is excessively rapid, demand-led, environmentally damaging or unevenly distributed. By contrast, productivity-driven, sustainable and inclusive growth can allow several macroeconomic objectives to be achieved simultaneously.
Question
(a) Using an AD/AS diagram, explain why in the monetarist/new classical model an economy will always operate at the natural rate of unemployment in the long run. [10]
(b) Using real-world examples, discuss the view that high unemployment is a greater economic problem than high inflation. [15]
Most-appropriate topic code (CED):
• TOPIC 3.3: Macroeconomic objectives – part (b)
▶️ Answer/Explanation
(a) Answer:
The monetarist/new classical model argues that, in the long run, the economy will return to its natural rate of unemployment. The natural rate of unemployment is the level of unemployment that exists when the labour market is in equilibrium, including frictional and structural unemployment. It is therefore consistent with the economy operating at its long-run potential level of output.
In this model, long-run aggregate supply (LRAS) is vertical at the economy’s potential output. This means that the long-run level of real output is determined by factors such as the quantity and quality of resources, technology and productivity rather than by the price level.
In the short run, a change in aggregate demand (AD) can cause the economy to operate away from potential output. For example, suppose AD increases from AD1 to AD2. In the short run, because wages and prices are not completely flexible, the economy can move to an equilibrium where AD2 intersects SRAS to the right of LRAS. Real output temporarily rises above its potential level and unemployment falls below the natural rate. This creates an inflationary gap.
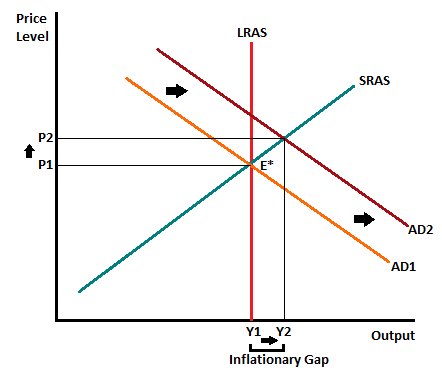
However, according to the monetarist/new classical model, this situation cannot persist in the long run. As demand increases, firms experience higher costs and workers demand higher money wages as they respond to tighter labour-market conditions. As wages and other costs rise, the SRAS curve shifts leftwards.
The adjustment continues until the economy returns to the level of output determined by LRAS. The price level will be higher, but real output returns to its potential level. At this point, unemployment returns to the natural rate.
A similar process occurs following a decrease in AD. In the short run, lower AD may reduce real output below potential output and cause unemployment to rise above the natural rate, creating a deflationary gap. However, lower demand for labour puts downward pressure on wages. Since wages and prices are assumed to be flexible in the long run, falling costs cause SRAS to shift rightwards.
The economy eventually returns to the level of output on the LRAS curve. Therefore, the temporary deviation in unemployment disappears and unemployment returns to its natural rate.
The central assumption is therefore that money wages and prices are flexible in the long run. Changes in AD can create temporary inflationary or deflationary gaps, but wage and price adjustments eliminate these gaps. Changes in AD consequently affect the price level in the long run rather than permanently changing real output or unemployment.
Therefore, in the monetarist/new classical model, the economy will always return to its potential output in the long run. Since the natural rate of unemployment is associated with this level of output, the economy will operate at the natural rate of unemployment in the long run.
(b) Answer:
Unemployment occurs when people who are willing and able to work at the prevailing wage rate are unable to find employment. Inflation is a sustained increase in the general price level, which reduces the purchasing power of money. Both can impose significant costs on an economy, but whether high unemployment is a greater problem depends on the magnitude, type and duration of the problem.
High unemployment can create significant economic costs. When workers are unemployed, the economy produces below its potential level of output because available labour resources are not fully utilized. This represents an opportunity cost because goods and services that could have been produced are lost. The government may also receive less income-tax revenue while paying more unemployment-related benefits, worsening the fiscal position.
There can also be substantial personal and social costs. Long periods of unemployment can reduce household income and living standards. Workers may lose skills and experience hysteresis, making it more difficult to return to employment. Persistent unemployment can therefore reduce future productive capacity as well as current output.
The experience of Spain following the global financial crisis illustrates the seriousness of unemployment. Spain experienced very high unemployment, particularly among young people, following the collapse of the housing boom and subsequent recession. The prolonged lack of employment opportunities reduced household incomes and contributed to significant social costs. This supports the argument that high unemployment can be a severe economic and social problem when it persists for a long period.
High unemployment can also reduce economic well-being and equity. The burden of unemployment is not distributed equally, since young workers, low-skilled workers and workers in declining industries may experience disproportionately high unemployment. Long-term unemployment can therefore increase inequality and reduce social cohesion.
However, high inflation can also impose substantial costs. One important cost is uncertainty. When inflation is high and unpredictable, households and firms find it more difficult to plan consumption, saving and investment decisions. Firms may also face difficulty forecasting future costs and revenues.
Inflation can also create redistributive effects. People whose incomes or pensions do not adjust fully with the price level may experience a fall in real income. Similarly, savers may lose purchasing power if the nominal interest rate on their savings is below the inflation rate. In contrast, some borrowers may benefit because the real value of their debts falls.
High inflation may also reduce international competitiveness. If domestic prices rise faster than those of trading partners, exports may become relatively more expensive. This can reduce export demand and increase the demand for imports, potentially worsening the current account balance.
A major real-world example is Zimbabwe, which experienced extremely high inflation in the late 2000s. The rapid loss of purchasing power severely disrupted the economy, weakened the usefulness of the domestic currency as a medium of exchange and store of value, and made economic decision-making extremely difficult. This demonstrates that sufficiently high inflation can become a much greater problem than moderate unemployment.
High inflation can also affect economic growth. If inflation becomes unpredictable, firms may postpone investment because they are uncertain about future costs and returns. Inflation can therefore reduce efficient resource allocation and potentially weaken long-run economic growth.
Nevertheless, the comparison depends on the magnitude of the problem. Moderate inflation may impose relatively limited costs, particularly if it is predictable and wages and incomes adjust with prices. In contrast, very high and unstable inflation can cause serious disruption to saving, investment, consumption and international trade.
Similarly, a low rate of unemployment may not represent a major economic problem if most unemployment is frictional and temporary. However, persistent structural or long-term unemployment can be much more damaging because workers may lose skills and become less employable. Therefore, the type and duration of unemployment are important when comparing its costs with inflation.
There can also be a trade-off between the two objectives in the short run. Expansionary demand-side policies may increase AD and reduce cyclical unemployment, but if the economy is already close to full employment, the additional demand may create greater inflationary pressure. Policymakers therefore need to consider the conditions of the economy before deciding which problem is more serious.
Overall evaluation: The view that high unemployment is a greater economic problem than high inflation is not universally valid. High unemployment can be particularly damaging when it is persistent, structural or associated with a large output gap, because it creates lost output, lower incomes, fiscal costs and significant personal and social costs.
However, extremely high or unpredictable inflation can be even more damaging. The Zimbabwean experience demonstrates that very high inflation can severely disrupt the functioning of an economy, while moderate and predictable inflation may have comparatively limited costs.
Therefore, the relative seriousness depends primarily on the magnitude, duration and type of unemployment or inflation. In a recession with widespread long-term unemployment, unemployment is likely to be the greater immediate economic problem. Conversely, when inflation becomes extremely high and unstable, controlling inflation may take priority. Thus, neither objective can be considered universally more important; the appropriate policy priority depends on the specific economic circumstances.